
A strong credit history can lower borrowing costs, expand approval options, and reduce the friction of everyday milestones like renting an apartment, setting up utilities, or financing a car. Credit building isn’t about “hacks”—it’s about repeating a few high-impact behaviors long enough for your credit reports to reflect them. The steps below break credit scoring into clear levers—payment history, utilization, age of accounts, credit mix, and inquiries—then turn them into practical actions you can start this week.
Your credit history is the record of how you’ve managed credit over time: on-time payments, balances, limits, and how long accounts have been open. A strong history tends to look steady—few or no missed payments, reasonable balances compared to limits, older accounts kept in good standing, and limited risky behavior like frequent new applications.
Credit scores are summaries calculated from the data in your credit reports. Improving the score usually follows improving the underlying habits that feed the reports. Expect gradual change: small improvements can show up as your balances drop and new on-time payments post, while a long, clean track record typically takes years.
Most scoring models weigh certain behaviors more heavily than others. If you’re new to credit or rebuilding, prioritize what prevents damage first (missed payments), then what reduces risk signals (high utilization), and only then consider optional boosts like adding new accounts.
| Factor | Why it matters | Beginner-friendly actions |
|---|---|---|
| Payment history | Shows reliability and consistency | Autopay minimum; pay before due date; use alerts; avoid late fees |
| Utilization | Signals how much of available credit is being used | Pay mid-cycle; keep balances low; request limit increases when eligible |
| Length of history | Rewards stability over time | Keep oldest card open; avoid frequent account churn |
| New credit | Too many applications can look risky | Apply only with a plan; space applications; monitor hard inquiries |
| Credit mix | Can help when managed well | Add accounts only when needed; focus on affordability first |
For additional context on how credit reports and scores work, the Consumer Financial Protection Bureau provides a clear overview here: Consumer Financial Protection Bureau — Credit reports and scores. For fundamentals of score components, see: FICO — Credit score fundamentals.
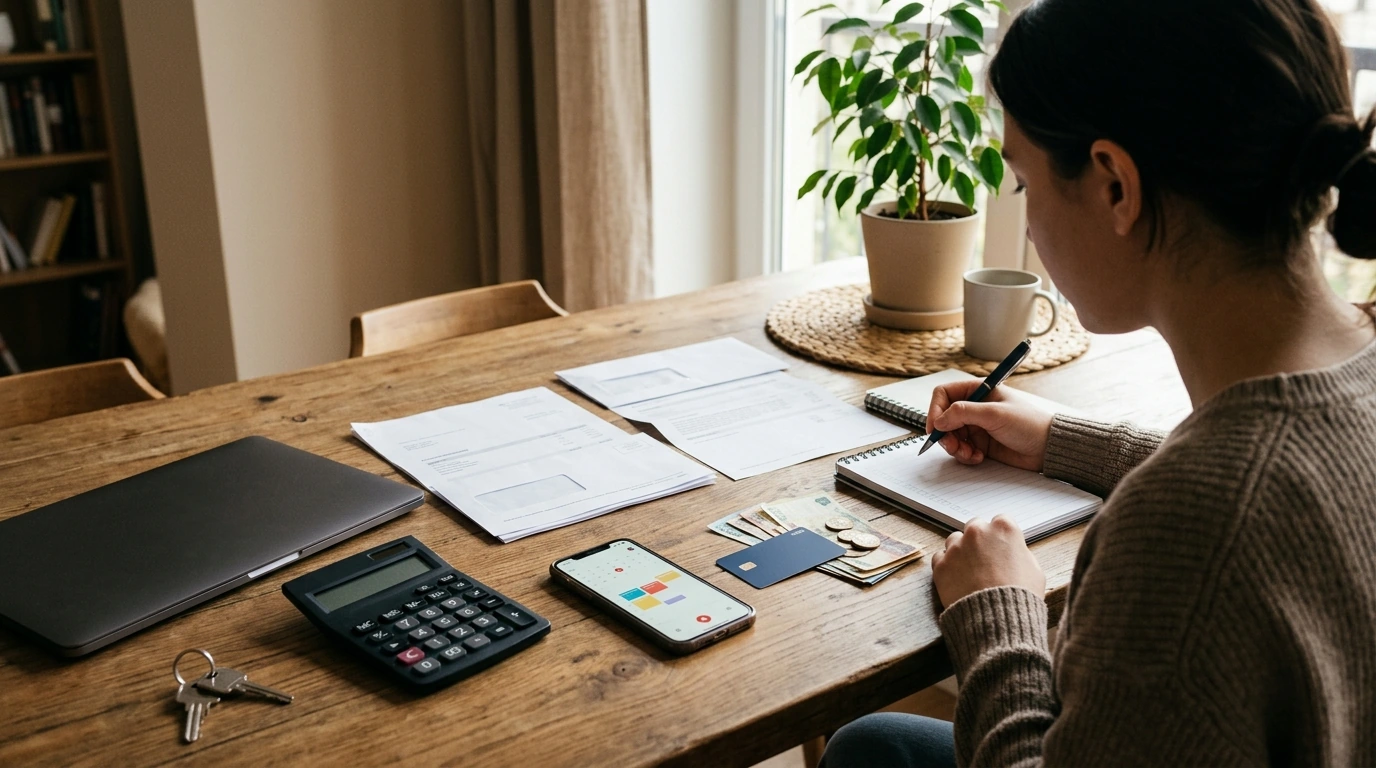
Pull your credit reports, list every open account, and write down due dates and minimum payments. If you spot obvious errors (wrong balances, accounts you don’t recognize, incorrect late payments), dispute them with documentation. For official guidance on free reports and disputes, use: Federal Trade Commission — Credit reports (disputes and accuracy).
Bring any past-due accounts current as fast as possible, then set autopay for at least the minimum payment on every account. Add reminders a few days before each due date so you can confirm payments post. If balances are high, start targeted payments on revolving accounts (credit cards) where utilization is likely hurting you most.
If you pay in full, keep doing that—but change timing if needed. Utilization is based on what gets reported, which often happens around statement closing. Paying before the statement date can lower the reported balance. If cash flow is tight, consider multiple smaller payments during the month to keep balances from climbing.
If you have limited credit history, evaluate whether a secured card or a credit-builder loan is a good fit. Avoid applying for multiple new accounts “just to build credit.” Track progress monthly, not daily—scores can swing while reports update, but consistent habits are what win.
| When | Task | Time needed |
|---|---|---|
| Weekly | Review balances and upcoming due dates | 5–10 minutes |
| Weekly | Make an extra payment toward revolving balances (if possible) | 2–5 minutes |
| Monthly | Review statements for fees/interest and adjust payment timing | 10–15 minutes |
| Monthly | Check credit report updates or alerts | 10–20 minutes |
Proven Ways to Build a Strong Credit History (downloadable guide and checklist) is designed to turn the key credit habits—report review, payment timing, utilization strategy, and realistic milestones—into an action plan you can reuse.
To stay consistent with any money goal, tracking helps. Pair your credit routine with a simple progress system like Creative Hobby Progress Tracker Ideas – Digital Ebook Guide to borrow practical tracking methods you can adapt for payments, due dates, and monthly check-ins.
Small improvements can appear in 1–3 months once on-time payments post and reported utilization drops. A strong, stable history usually takes 12+ months, with bigger gains over several years of consistent behavior.
Paying in full is typically best because it avoids interest and still builds credit through on-time payments. What matters most is paying on time and keeping the balance that reports at statement time relatively low.
Aim to keep utilization comfortably low and avoid maxing out cards. Lower is generally better, and paying before the statement date can help control what balance gets reported.










Leave a comment