
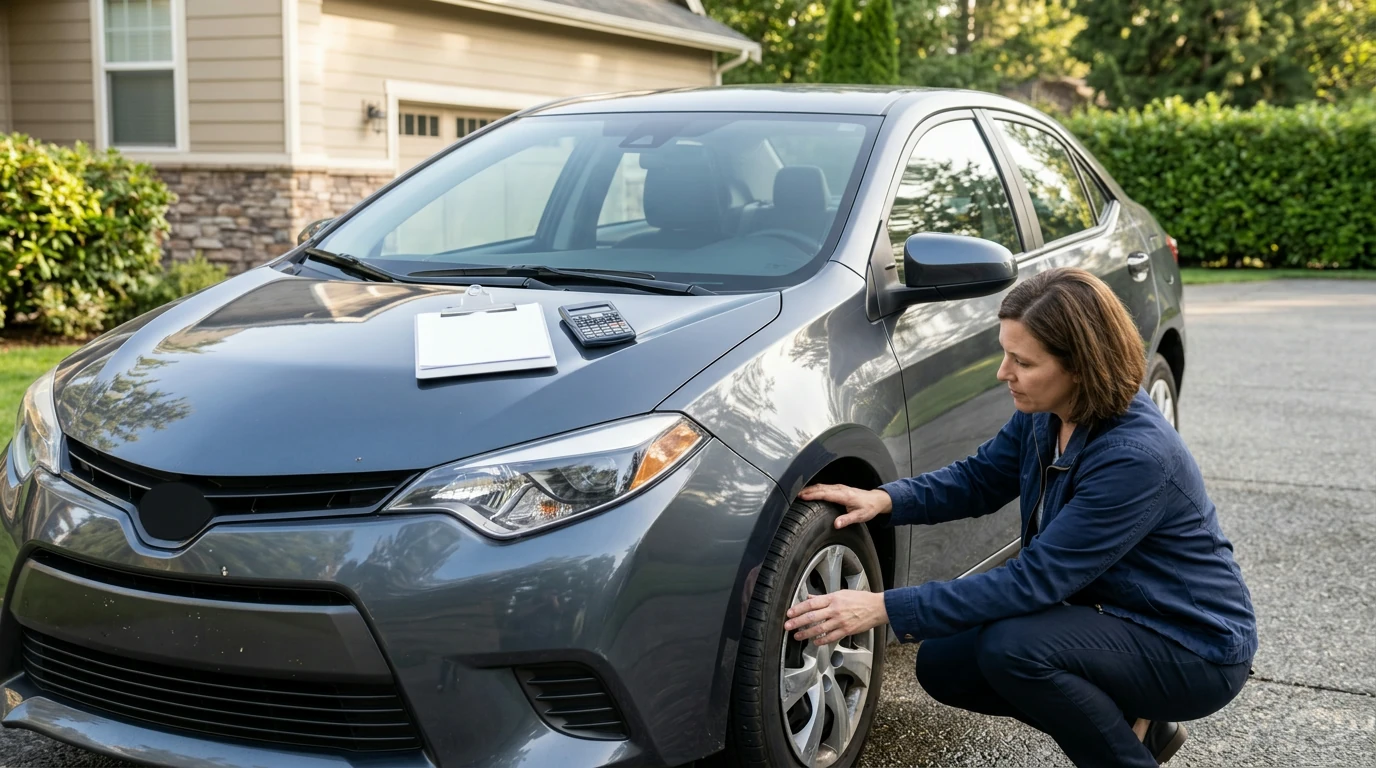
Sometimes, but only when the numbers (and your timeline) cooperate. Ending a lease early can make sense if your needs changed—like a new commute, growing family, or wanting a different vehicle—and the cost to exit is lower than the cost of staying put. It can also be worthwhile when your leased car’s market value is strong enough to offset what you still owe.
The catch is that early lease termination is rarely “free.” Many leases require paying remaining payments, an early termination fee, and possibly disposition or other charges. Depending on the contract, you may also need to cover the difference between what the car is worth and what the leasing company expects to recover.
Exiting early tends to be smarter when you’re close to the end of the lease, when your vehicle has equity (its value exceeds the buyout), or when a lease transfer is allowed and easy to arrange. It may also make sense if you can buy the car and sell or trade it for more than the buyout—though taxes and fees can erase that advantage.
If you’re early in the lease, the remaining payments and termination costs can be steep. It’s also riskier when the buyout is higher than the car’s current value; you could pay a large shortfall just to walk away.
Start by pulling your lease payoff/buyout quote and asking what fees apply to early termination. Then compare that total to the cost of keeping the lease until the end, and to alternatives like transferring the lease or trading the vehicle. For a step-by-step checklist and payoff math, see this guide to ending a car lease early.
Many leases allow transfers, but you’ll need the lessor’s approval and the new driver must pass a credit check. Transfer fees may apply, and some brands don’t permit transfers at all.









Leave a comment